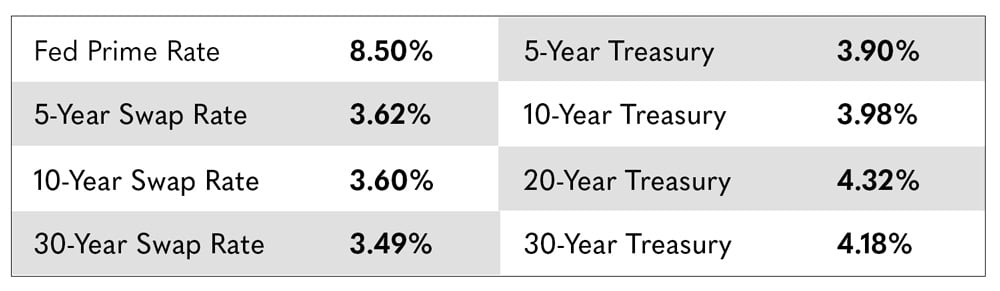
Presently, 10-year Treasuries stand at 4.04%, marking a week-over-week increase of 6 basis points.
Weekly Trading Range:
Throughout the preceding week, 10-year Treasuries exhibited a fluctuation within a 20-basis point range. Notably, the range extended from an intraday low of 3.90% on Wednesday to a peak of 4.10% on Friday morning, coinciding with the release of a robust employment report.
Momentum Shift Over Two Weeks:
While 10-year rates had shown an impressive improvement of over 100 basis points since the peak of 5.02% on October 23, 2023, the momentum witnessed a recent two-week slowdown.
Unexpected Reaction to December 22nd Events:
On December 22nd, despite exceptionally favorable PCE index inflation numbers (with a top-line PCE index of -0.1% month-over-month and 2.6% year-over-year), the anticipated rally in interest rates did not materialize. Instead, 10-year rates experienced a 4-basis point increase on that particular day.
Tug-of-War in Treasury Prices on Recent Friday:
This past Friday saw Treasury prices engaged in a tug-of-war scenario with economic data.
December Employment Report Highlights:
The US employment report for December showcased another round of "better-than-expected" results. Non-farm payrolls saw an addition of 216,000 new jobs, surpassing the consensus expectation of 175,000. Meanwhile, the unemployment rate remained steadfast at 3.7%, mirroring the November figures.
Market Perception and Fed Expectations:
Within the bond market, there has been a prevailing sentiment that the Federal Reserve would initiate a Fed Funds rate cut as early as March, potentially reaching a significant reduction of 150 basis points by the close of 2024.
Contradictory Evidence in December Employment Report:
The December employment report, contrary to market expectations of an early and aggressive Fed response, presented evidence against such a move. Consequently, interest rates responded by moving incrementally higher in the aftermath.
Recent Transactions
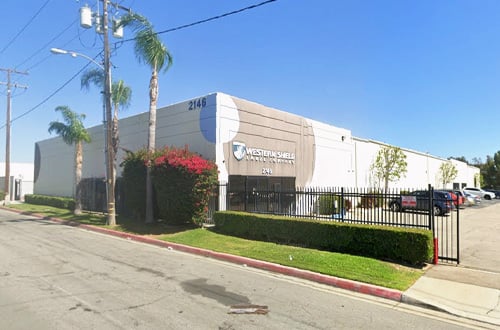
$2,800,000 Refinance of an Industrial Property in Compton, California.
FINANCED Gladwick Industrial
Property Type: Industrial
Lender: Life Insurance Company City: Compton, California Size: 27,000 SF Term: 5+5-year loan, 30-year amortization
Dave Semmer of PSRS arranged the $2.8 million refinance of an industrial property in Compton, California. The subject property is a one-story, 27,000-square-foot light industrial property built in 1972 and located in the Rancho Dominguez submarket of Los Angeles. Financed with one of our correspondent life insurance companies, PSRS provided its borrower with an interest-only, non-recourse loan with a 5+5-year term and 30-year amortization after the initial interest-only period burned off.
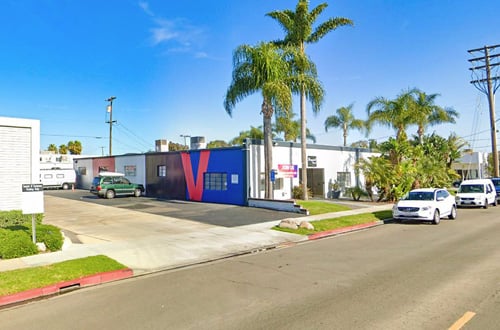
$1,030,000 Cash-Out Refinance of a Flex Property in Newport Beach, California.
FINANCED Newport Beach Flex
Property Type: Flex/Industrial
Lender: Life Insurance Company City: Newport Beach, California Size: 10,000 SF Term: 5+5-year term, 30-year amortization
David Smyle of PSRS arranged the $1.03 million cash-out refinance of a flex property in Newport Beach, California. The subject property is a freestanding two-tenant flex/industrial building totaling 10,000 rentable square feet. Built in 1965, the building combines masonry block and concrete tilt-up construction with flat built-up composition roofing. Financed with one of our correspondent life insurance companies, PSRS provided its borrower a 26% LTV, sub-7% loan with a ten-year (5+5) term and a 30-year amortization.
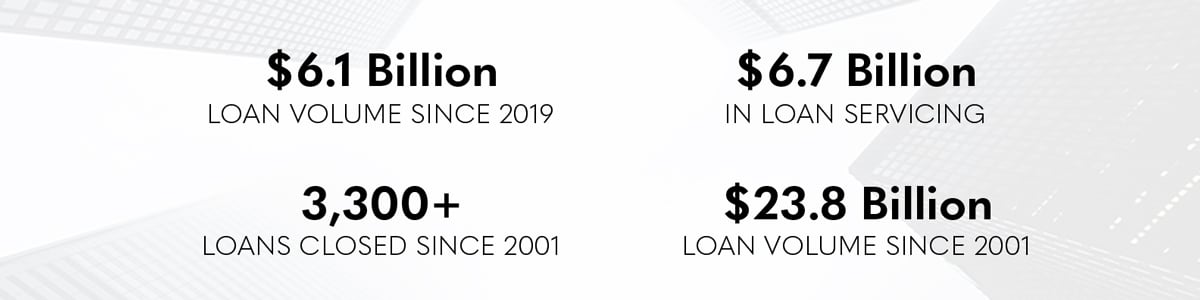
About PSRS Founded in 1972, PSRS is a commercial mortgage banking firm that helps real estate investors of all sizes structure and secure financing solutions that align with their investment goals.